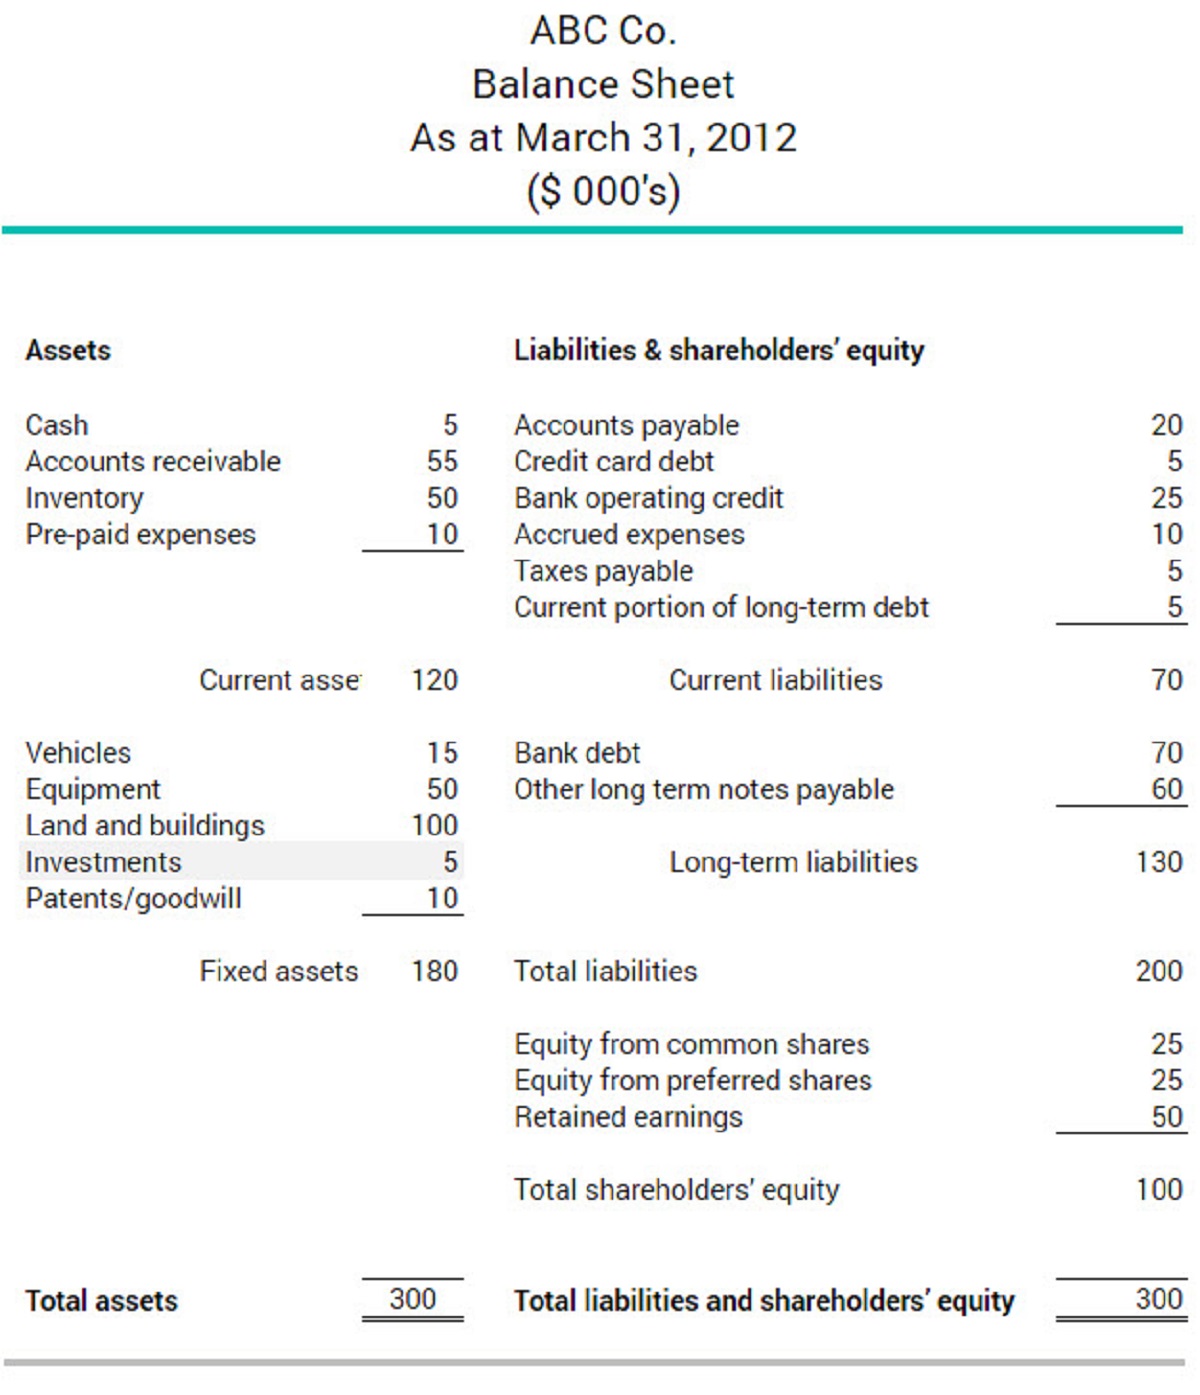
All investments on the balance sheet are reported as assets, and they are immediately categorized as either current or non-current (long-term) based on their maturity and liquidity. This classification is fundamental: investments expected to be converted to cash within one year are placed in the current assets section, while those held for longer than one year are classified as non-current assets. The placement directly signals to stakeholders how quickly the company can access the invested funds and reflects the company's investment strategy.
Where do investments go on the balance sheet?
Investments are always recorded as assets on the balance sheet, never as liabilities or equity. The specific line item and section depend on the investment's holding period and liquidity. Short-term, highly liquid investments appear under Current Assets, typically after cash and cash equivalents. Long-term investments, held for more than one year, are placed under Non-Current Assets, often in a dedicated line item such as "Long-Term Investments" or "Investments and Other Assets." This clear separation allows users of financial statements to distinguish between funds available for near-term use and those committed to longer-term strategic objectives.
Investments as current assets
Current investments, also known as short-term investments, are assets that are expected to be converted into cash within one year or the operating cycle of the business, whichever is longer. These are highly liquid instruments such as Treasury bills, commercial paper, money market funds, and short-term bonds. On the balance sheet, they are listed under the Current Assets section, usually immediately after cash and cash equivalents, because they are the next most liquid assets after cash.
Current investments are reported at their fair value, which represents the price that would be received from selling the investment in an orderly transaction between market participants at the measurement date. Any changes in fair value are recognized in the income statement as unrealized gains or losses (if still held) or realized gains or losses (if sold). This fair value presentation provides a more accurate picture of the company's short-term financial position than historical cost.
The presentation can be as a single aggregated line item (e.g., "Marketable Securities") or broken out individually, depending on the level of detail the company chooses. Additional information about the types, quantities, and fair values of these investments is typically disclosed in the footnotes to the financial statements, offering transparency about the company's short-term investment activities.
Investments as long-term (non-current) assets
Long-term investments are assets held for more than one year, reflecting a company's commitment of funds for future growth, income generation, or strategic purposes. These can include stocks, bonds, real estate properties, venture capital, private equity, or ownership stakes in other companies. On the balance sheet, they are classified as Non-Current Assets and are presented separately from current investments to distinguish between short-term liquidity and long-term capital allocation.
This separate presentation helps stakeholders assess the company's long-term investment strategy and its ability to generate future returns from these holdings.
The valuation of long-term investments on the balance sheet depends on the accounting method used (see next section). They may be reported at historical cost, fair value, or using the equity method. Changes in fair value for available-for-sale securities are recorded in other comprehensive income (equity) rather than the income statement, unless the investment is impaired or sold. This treatment keeps the balance sheet reflective of current market conditions while not distorting periodic earnings.
How accounting methods affect the reported value
The dollar figure shown for long-term investments on the balance sheet is determined by the accounting method applied, which depends on the type of investment and the level of influence the company holds. There are three primary methods:
- Cost Method: Used when the company has no significant influence over the investee (typically less than 20% ownership). The investment is recorded at historical cost and remains at that cost unless there is an other-than-temporary impairment. Dividends received are recognized as income, but changes in fair value are not recorded on the balance sheet.
- Equity Method: Applied when the company has significant influence (usually 20% to 50% ownership) but not control. The investment is initially recorded at cost, then adjusted annually for the company's share of the investee's profits or losses. Dividends received reduce the carrying amount. This method reflects the economic reality of the investment's performance on the balance sheet.
- Fair Value Method: Used for investments where the company has no significant influence and the securities are publicly traded (e.g., available-for-sale or trading securities). The investment is reported at its current market value. Unrealized gains or losses on available-for-sale securities are recorded in other comprehensive income (equity), while trading securities recognize changes in the income statement. This method provides the most current valuation but introduces volatility to the balance sheet.
The choice of method directly impacts the reported asset value and the recognition of gains or losses. Companies must consistently apply the appropriate method based on ownership percentage and influence, ensuring that the balance sheet accurately reflects the economic substance of the investment.
Disclosure requirements for balance sheet investments
Beyond the single line item on the balance sheet, companies must provide detailed disclosures in the footnotes to the financial statements. These disclosures include the type of investments held (equity, debt, real estate, etc.), the quantity or number of shares, the cost basis, the fair value at the reporting date, and any restrictions or contingencies associated with the investments.
For long-term investments, additional disclosures may include the accounting method used, the existence of any impairment losses, and the impact of unrealized gains or losses on equity. For current investments, the footnotes often break down the composition (e.g., Treasury bills vs. money market funds) and any maturities. These disclosures provide transparency beyond the balance sheet line item, allowing investors, auditors, and regulators to understand the nature, risk, and valuation of the company's investment portfolio.
Disclosure requirements are governed by accounting standards such as GAAP (Generally Accepted Accounting Principles) or IFRS (International Financial Reporting Standards), which mandate specific footnote schedules for investments. This ensures that stakeholders have sufficient information to make informed decisions about the company's financial health and investment strategy.