Kick off lending is a peer-to-peer (P2P) lending model where individual investors directly fund loans for borrowers through online platforms, bypassing traditional banks. The term often gets confused with Kikoff, a separate company offering a credit-building service you can cancel anytime, but the core concept remains the same: technology connects people who need money with people who want to earn returns on it. This article explains how kick off lending works for both borrowers and investors, its advantages, and the risks you must weigh before participating.
What is kick off lending
Kick off lending, also known as peer-to-peer lending, is an alternative financing system that removes the intermediary from the lending process. Instead of a bank deciding who gets a loan and at what rate, an online platform matches borrowers with individual lenders. Each loan is funded by multiple investors who pool their money, and the platform handles credit checks, payment collection, and distribution. This structure creates a decentralized lending ecosystem where borrowers often access competitive rates and investors gain a new asset class. The specific company Kikoff, which shares a similar-sounding name, operates differently, it focuses on building credit through small, reported installment loans and offers a subscription service you can cancel anytime.
How kick off lending works for borrowers
For borrowers, the process is designed to be faster and more accessible than traditional lending. The journey follows a clear sequence:
- Submit an online application with personal details, income information, employment history, and the loan’s purpose.
- The platform runs a credit assessment, checking your credit score and verifying the information you provided.
- If approved, your loan request is listed on the platform with the amount, interest rate, and repayment term.
- Investors review your listing and decide whether to fund all or part of it.
- Once fully funded, the platform disburses the money directly to your bank account.
- You repay in fixed monthly installments, which include principal and interest, through the platform.
The key benefit is speed, approval often takes days rather than weeks. Interest rates are typically lower than payday loans or credit cards, especially for borrowers with good credit, because platforms operate with lower overhead than banks. However, you must meet the platform’s credit criteria, and the rate you receive depends on your risk profile. Unlike Kikoff, which reports small payments to credit bureaus to help you build history, kick off lending platforms focus on larger, unsecured personal loans.
How kick off lending works for investors
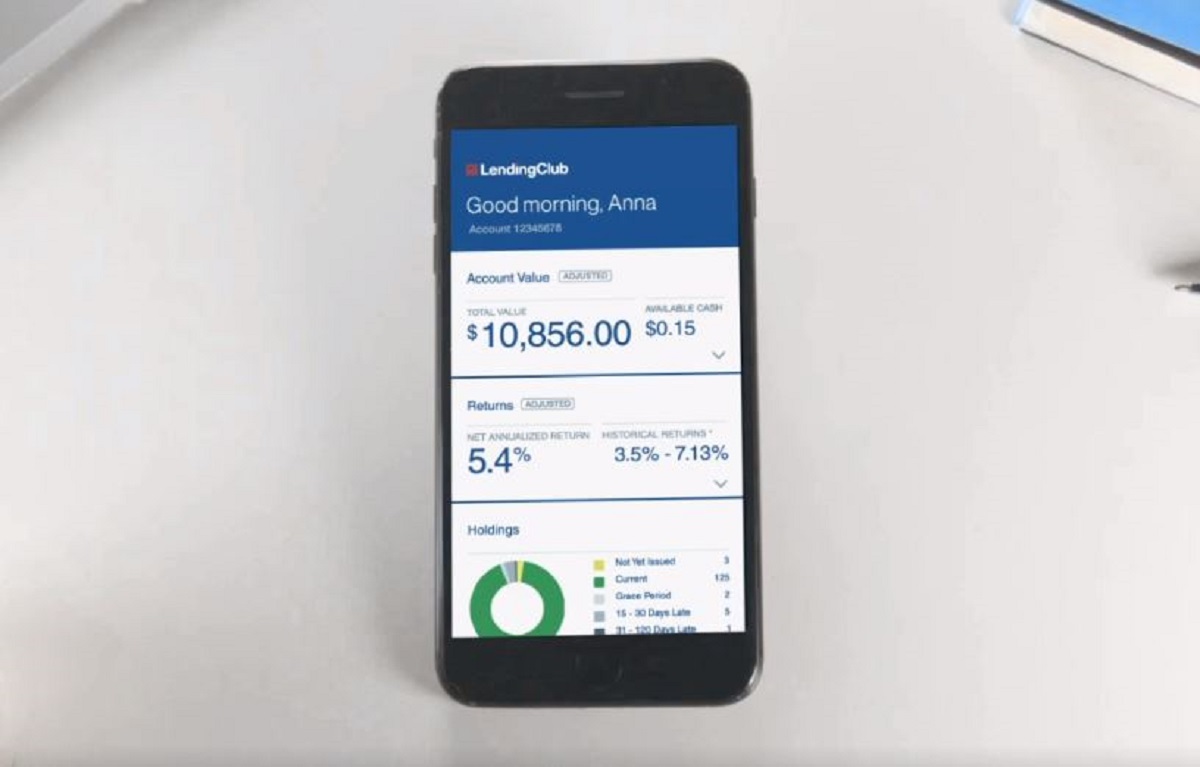
Investors, also called lenders, take on the role traditionally held by banks. After registering on a platform, you browse available loan listings and select which ones to fund. Each listing shows the borrower’s credit grade, loan purpose, interest rate, and term. You can choose to fund a fraction of a loan or the entire amount, and most investors spread their money across many loans to reduce risk. The platform handles all administrative tasks, including collecting monthly payments from borrowers and distributing them to you proportionally.
Your returns come from the interest borrowers pay, minus any platform fees. Because you are lending directly, you earn the full interest rate rather than a small deposit rate from a savings account. The platform provides tools to filter loans by risk level, so you can align your investments with your tolerance for default. Diversification is critical, by funding 50 or 100 small loans instead of one large one, you protect yourself against any single borrower failing to repay.
Advantages of kick off lending
For borrowers, the main advantages are access, speed, and competitive rates. Kick off lending opens funding options for people who might be rejected by banks due to thin credit histories or self-employment income. The online application takes minutes, and funding arrives quickly, which is useful for emergencies or time-sensitive purchases. Because platforms have lower operating costs than brick-and-mortar banks, they can offer interest rates that undercut traditional personal loans for well-qualified borrowers.
For investors, the benefits include portfolio diversification, potential for higher returns, and direct control. You decide exactly which loans to fund, rather than buying a pooled bond or fund. This control lets you avoid industries or borrower profiles you dislike. Historically, P2P lending has delivered returns higher than savings accounts or government bonds, though past performance does not guarantee future results. The transparency of seeing each borrower’s credit grade and loan purpose helps you make informed decisions.
Risks and challenges to consider
Kick off lending carries real risks that differ from traditional investments. Default risk is the most significant, borrowers may stop making payments, and you could lose part or all of your principal. Even with credit screening, economic downturns increase default rates across the board. Unlike bank deposits, P2P loans are not insured by any government agency, so there is no safety net.
Platform instability is another concern. If the platform itself goes bankrupt or shuts down, your loans may become difficult to collect, and you could face delays or losses. Liquidity is also limited, your money is locked in for the loan term, which can range from 12 to 60 months. There is no guaranteed secondary market to sell your loans early, so you must be prepared to hold until maturity. Regulatory uncertainty adds another layer: P2P lending rules vary by country and are still evolving, which could affect how platforms operate or how your investments are treated legally.
Cautions before you start lending or borrowing
Before participating, conduct thorough due diligence on any platform. Check its track record, financial stability, and how long it has been operating. Read the fee structure carefully, borrowers often pay origination fees, while investors may pay a servicing fee or a percentage of interest earned. These costs reduce your net return or increase your effective interest rate, so factor them into your calculations.
Diversification is not optional; it is essential. Spread your investments across multiple loans with different risk grades, loan purposes, and terms. Never invest money you cannot afford to lose, and avoid borrowing money to invest in P2P loans, as this amplifies your risk. For borrowers, only take a loan if you are confident in your ability to make monthly payments, defaulting damages your credit score and may lead to collections. Finally, understand the legal framework in your jurisdiction and choose platforms that comply with local regulations. Kick off lending can be a valuable tool, but it rewards careful research and disciplined risk management.