Cash Concentration and Disbursement (CCD) is a corporate ACH payment format used by businesses to electronically move funds between their own accounts or with other companies, functioning as both a credit tool for making payments and a debit tool for collecting funds. In banking, what is CCD in banking comes down to a standardized, cost-effective way for businesses to consolidate cash from multiple accounts into one central account and to automate recurring payments like payroll or vendor invoices through the Automated Clearing House network.
What is CCD in banking?
Cash Concentration and Disbursement (CCD) is a specific ACH transaction format designed exclusively for business-to-business (B2B) electronic funds transfers. It enables a company to concentrate funds from various bank accounts into a single concentration account, or to disburse funds from that account to pay other businesses. CCD is governed by NACHA rules in the United States and is distinct from consumer-oriented ACH formats because it is limited to corporate entities, not individuals. The format supports both credit entries, where a business sends money to another business, and debit entries, where a business pulls money from another business's account with prior authorization.
How a CCD transaction works
A CCD transaction begins when a business initiates a payment file through its treasury management system, online banking platform, or accounting software. The initiating bank transmits this file in batches to the ACH network, where it is sorted and routed to the receiving bank. The ACH operator processes these batches at scheduled intervals throughout the day, and settlement typically occurs within one to two business days. During clearing, the originating bank debits the sender's account, and the receiving bank credits the recipient's account. The remittance data travels with the payment, allowing the receiving business to automatically reconcile the payment against open invoices without manual matching.
Initiation and file transmission
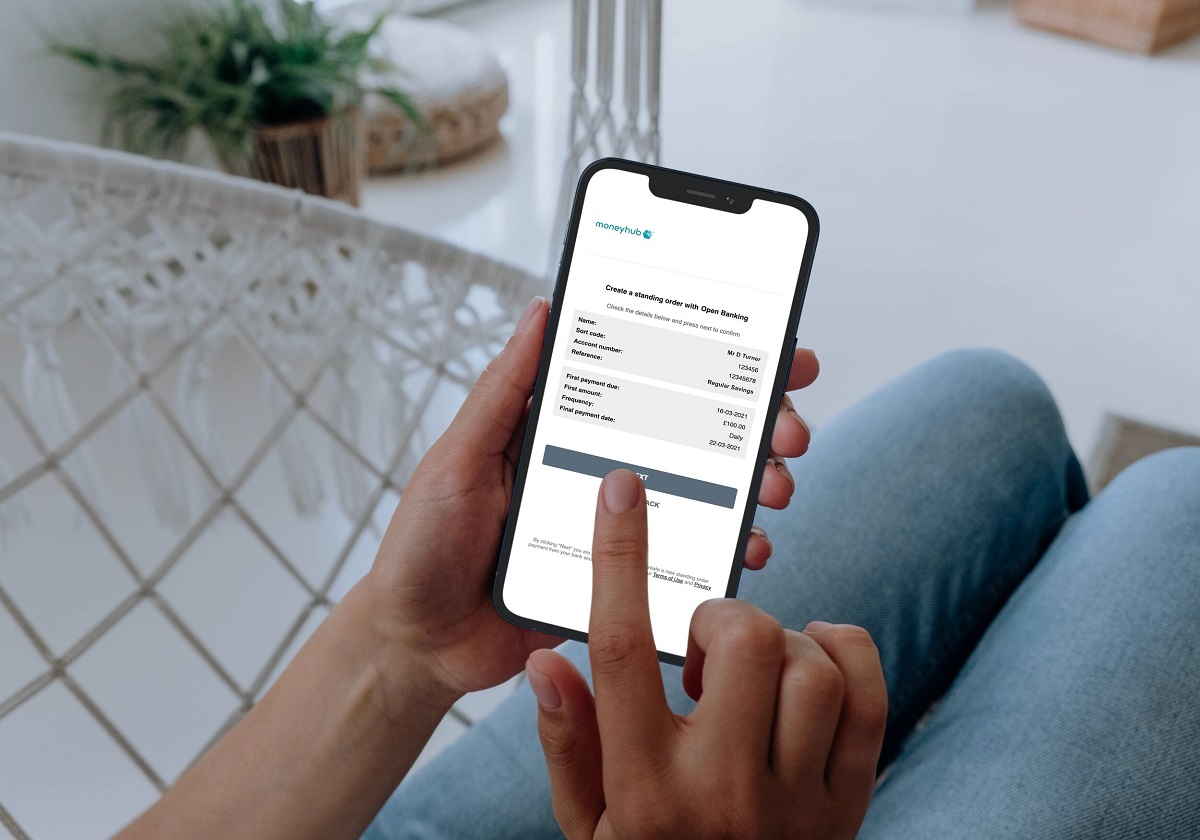
The business prepares a CCD payment file containing all required transaction details, then securely transmits it to its bank via encrypted file transfer protocols (SFTP) or through a direct API connection. The bank validates the file format against NACHA standards and checks that the originating account has sufficient funds or authorization for debit transactions.
Batch processing and clearing
The ACH network groups CCD transactions into batches with other ACH payments for efficient processing. The network operator sorts transactions by destination bank and delivers them in files, typically multiple times per business day. Clearing involves the exchange of payment instructions between banks, while settlement is the actual movement of funds, which occurs through the Federal Reserve's settlement system.
Confirmation and reconciliation
After settlement, both the originating and receiving banks provide transaction confirmations. The receiving business can use the remittance data in the CCD record to automatically match the payment to its accounts receivable, while the sending business reconciles the debit against its accounts payable records.
CCD credits vs. CCD debits
CCD transactions operate in two distinct modes, each serving a different business purpose. A CCD credit is initiated by the paying business to send funds to another business, this is commonly used for vendor payments, payroll disbursements to employees who bank at different institutions, or transferring funds between corporate accounts. For example, a manufacturer uses a CCD credit to pay its parts supplier each month, with the remittance field containing the purchase order number. A CCD debit, conversely, is initiated by the receiving business to pull funds from another business's account, but only with prior written authorization. This mode is ideal for collecting recurring payments, a waste management company uses CCD debits to automatically collect monthly service fees from its commercial customers, eliminating the need for those customers to manually initiate each payment.
Common use cases for CCD payments
Cash concentration is the most frequent application of CCD, where a retail chain with hundreds of store locations uses CCD debits to sweep daily sales receipts from each store's local bank account into a single corporate concentration account. This gives treasury teams real-time visibility into total cash position and enables more accurate forecasting. Payroll processing is another major use case, companies use CCD credits to deposit employee wages directly into bank accounts, bundling hundreds or thousands of payments into a single batch file. Vendor payments are equally common, particularly for businesses with high-volume, recurring supplier invoices. CCD is also used for one-time transfers between corporate entities, such as moving funds from an operating subsidiary to a parent company, and for insurance premium collections where insurers use CCD debits to automatically withdraw policy payments from business clients' accounts.
CCD compared to other electronic payments
Understanding how CCD differs from wire transfers and standard ACH credits helps businesses choose the right payment rail for each situation. However, CCD settles in one to two business days, while domestic wires settle on the same day, often within hours. Wire transfers are used for high-value, time-sensitive payments like real estate closings or emergency supplier payments, while CCD is designed for recurring, smaller-value B2B payments. Standard ACH credits can be used for both consumer and business payments, but CCD is restricted to corporate entities.
Security measures for CCD transactions
CCD transactions are protected by multiple layers of security that safeguard sensitive financial data and prevent unauthorized transfers. Multi-factor authentication (MFA) is mandatory for any user initiating or approving CCD transactions through online banking platforms, requiring at least two independent verification methods such as a password plus a one-time passcode sent to a mobile device, or biometric verification like fingerprint scanning. Additionally, NACHA rules require businesses to implement fraud detection procedures, including positive pay systems that verify each CCD debit against a list of authorized transactions before processing, and dual-approval workflows where two different authorized users must approve any payment above a set threshold.