What is a Dividend in Banking?
A dividend in banking is a portion of a bank's profits distributed to its shareholders as a return on their investment. When a bank earns net income, its board of directors decides whether to reinvest those earnings into the business or pay them out to shareholders, with the payment typically made in cash or additional shares of stock.
Dividends in banking represent a critical mechanism for sharing financial success with investors. Unlike interest payments on deposits, which are expenses for the bank, dividends are distributions of after-tax earnings. The decision to pay a dividend reflects the board's assessment of the bank's current profitability, future capital needs, and regulatory requirements. Banks that consistently pay dividends are generally viewed as financially stable and profitable, as they demonstrate the ability to generate earnings beyond what is needed to maintain their operations and meet capital adequacy standards.
The dividend process in banking is governed by both corporate law and banking regulations. While most publicly traded banks pay dividends quarterly, some may pay annually or semi-annually, and the specific schedule depends on the bank's dividend policy and financial performance. It is important to understand that not all banks pay dividends, smaller or newer institutions often reinvest all profits to fuel growth, and shareholders may benefit instead through capital appreciation as the bank's stock value increases over time.
Key Dividend Dates Every Investor Should Know
Understanding the timeline of dividend payments is essential for any investor seeking to receive dividends in banking. There are four critical dates in the dividend process, and missing any one of them can affect your eligibility to receive the payment.
Declaration Date
The declaration date is when the bank's board of directors formally announces the dividend. On this date, the board specifies the dividend amount per share, the ex-dividend date, the record date, and the payment date. This announcement is typically made through a press release and is a legally binding commitment by the bank to pay the dividend. The declaration date is important because it sets the expectations for shareholders and the market regarding upcoming payments.
Ex-Dividend Date
The ex-dividend date is the first day that a stock trades without the right to receive the declared dividend. To be eligible for the dividend, an investor must purchase the stock before this date. If you buy shares on or after the ex-dividend date, you will not receive the upcoming dividend payment. Conversely, if you sell your shares on or after the ex-dividend date, you will still receive the dividend because you held the shares before the ex-dividend date. This date is typically set one business day before the record date.
Record Date
The record date is the date by which an investor must be officially registered on the company's books as a shareholder to receive the dividend. The bank reviews its shareholder records on this date to determine who is entitled to the payment. Because stock trades take time to settle, the ex-dividend date is set before the record date to ensure that trades are processed correctly. Only shareholders of record as of the close of business on the record date will receive the dividend.
Payment Date
The payment date is the actual date when the bank distributes the dividend to eligible shareholders. This is when the cash is deposited into shareholders' brokerage accounts or when additional shares are issued in the case of stock dividends. The payment date is typically several weeks after the record date, giving the bank time to process the payments. For investors relying on dividend income, the payment date represents the moment when they receive their return on investment.
How Bank Dividends are Calculated
The calculation of dividends in banking involves several financial metrics that determine both the total amount distributed and the attractiveness of the dividend to investors. Understanding these calculations helps investors evaluate whether a bank's dividend is sustainable and competitive.
The most fundamental metric is the dividend payout ratio, which is calculated by dividing the total amount of dividends paid by the bank by its net income. For example, if a bank has net income of $10 million and pays out $2 million in dividends, the dividend payout ratio would be 20%. This ratio indicates what percentage of earnings the bank is returning to shareholders versus retaining for future growth. Banks typically establish a target payout ratio range based on their strategic objectives and regulatory requirements.
The dividend yield is another crucial metric that investors use to assess the attractiveness of a bank's dividend. It is calculated by dividing the annual dividend per share by the stock's current market price. For instance, if a bank pays an annual dividend of $2 per share and its stock trades at $50, the dividend yield would be 4%. A higher dividend yield can make a bank's stock more appealing to income-focused investors, but it may also indicate that the stock price has declined or that the dividend is unsustainably high.
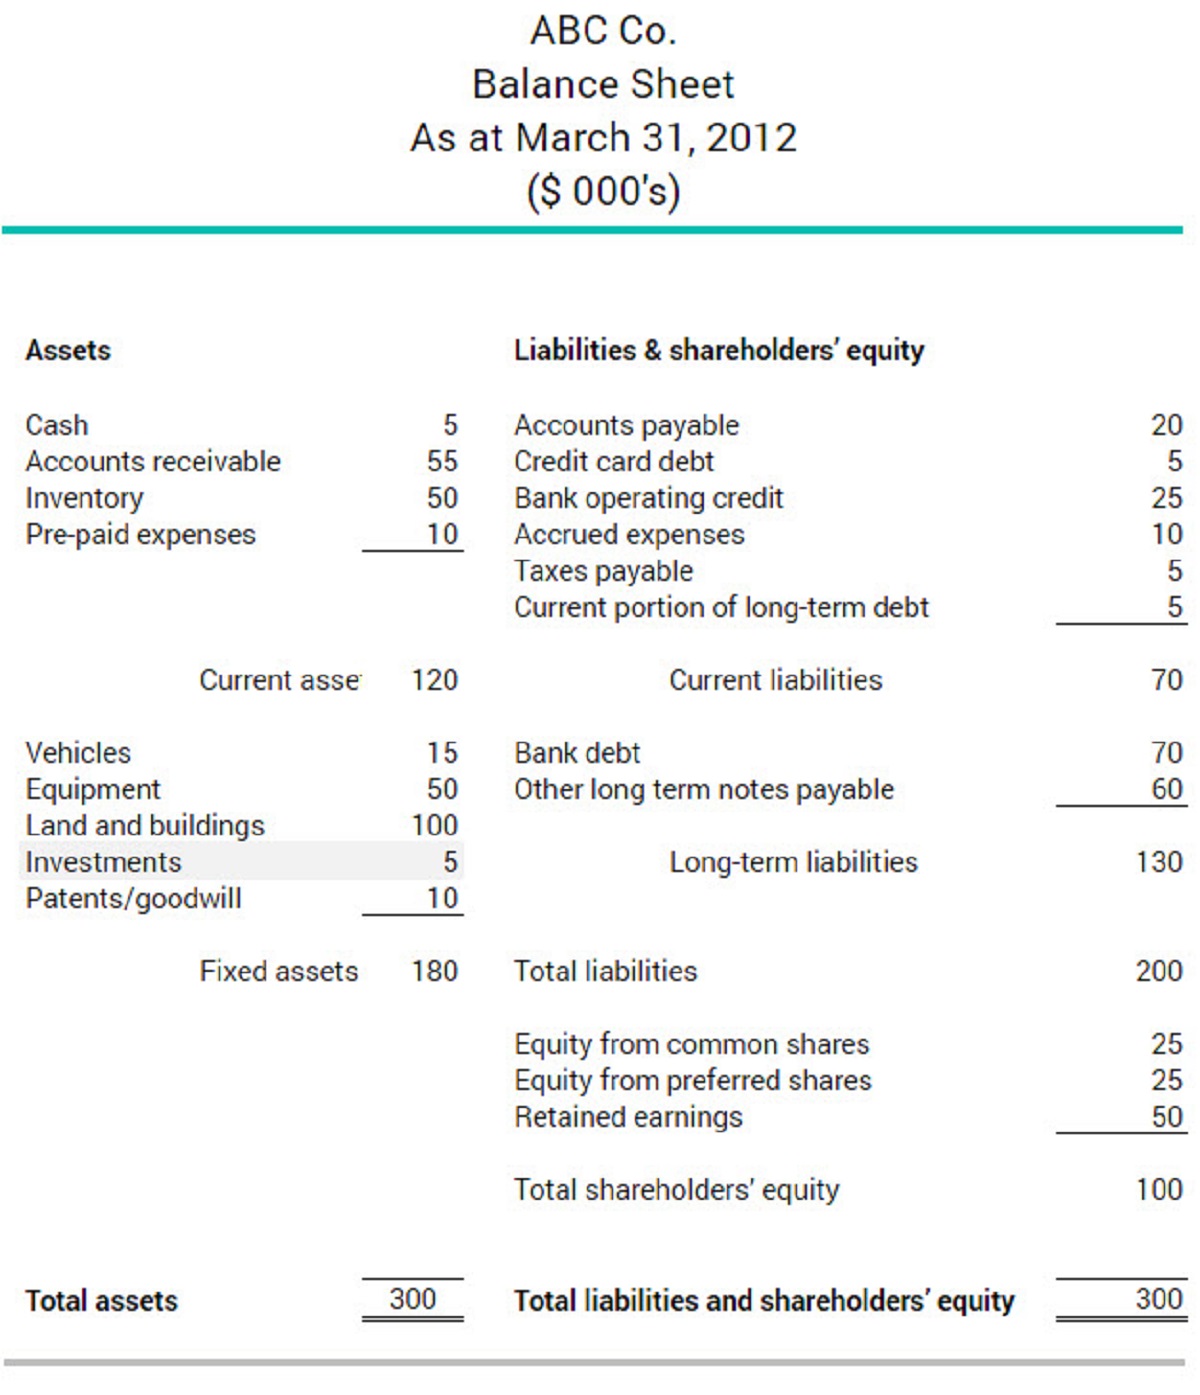
Retained earnings play a significant role in dividend calculations. These are the profits that the bank reinvests rather than distributes. Banks must balance the need to retain earnings for future growth, capital requirements, and potential economic downturns against the desire to reward shareholders. Regulatory capital requirements, which mandate minimum levels of capital relative to risk-weighted assets, often influence how much a bank can afford to pay out in dividends.
The number of outstanding shares also affects dividend calculations. Since dividends are paid on a per-share basis, the total dividend payout equals the dividend per share multiplied by the total number of outstanding shares. When a bank issues new shares or repurchases existing ones, the total dividend obligation changes accordingly. Banks that repurchase shares can maintain or increase their total dividend payout while reducing the per-share cost, which is why share buybacks are often paired with dividend payments.
Common Types of Dividends in Banking
Banks in the financial industry may distribute dividends in several forms, each with distinct characteristics and implications for shareholders. Understanding the different types helps investors know what to expect and how to evaluate their investment returns.
Cash Dividends
Cash dividends are the most common type of dividend in the banking sector. Shareholders receive the dividend directly in the form of cash, typically deposited into their brokerage accounts. The amount paid depends on the bank's profitability, dividend policy, and the number of shares held by each investor. Cash dividends provide immediate liquidity to shareholders, making them particularly attractive to income-focused investors who rely on regular cash flow from their investments. Most major banks pay cash dividends on a quarterly basis, though some may pay semi-annually or annually.
Stock Dividends
Stock dividends, also known as bonus shares or scrip dividends, are paid in the form of additional shares of the bank's stock rather than cash. For example, if a shareholder owns 100 shares and the bank declares a 10% stock dividend, they would receive an additional 10 shares. Stock dividends increase the number of shares held by investors but do not change the overall value of their investment, as the stock price adjusts proportionally. Banks may choose stock dividends to conserve cash while still rewarding shareholders, particularly when they want to retain capital for regulatory purposes or growth opportunities.
Special Dividends
Special dividends are one-time distributions that banks may pay in addition to their regular dividends. These are typically larger than regular dividends and may be triggered by exceptional performance, asset sales, or excess capital accumulation. Special dividends can be paid in cash or stock, depending on the bank's financial situation and strategic preferences. Shareholders often view special dividends as a bonus and a reflection of the bank's exceptional performance. However, because they are non-recurring, investors should not rely on them for regular income planning.
Why Banks Choose to Pay Dividends
Banks have several strategic reasons for paying dividends to their shareholders, ranging from financial management to market positioning. These motivations help explain why dividend policies are a central component of banking strategy.
Rewarding shareholders is the most direct reason for paying dividends. Shareholders provide the capital that banks need to operate and grow, and dividends offer a tangible return on that investment. By distributing a portion of profits, banks can incentivize investors to maintain their positions and attract new investors seeking reliable income streams. Dividends also demonstrate the bank's commitment to its shareholders, helping to build trust and confidence in the institution.
Paying dividends signals financial stability and profitability to the market. Banks that consistently pay dividends demonstrate their ability to generate consistent earnings, which is a key indicator of financial health. This signal is particularly important in the banking industry, where trust and confidence are essential for attracting deposits and maintaining customer relationships. A stable dividend history can differentiate a bank from competitors and enhance its reputation in the financial markets.
Managing excess liquidity is another strategic reason for paying dividends. When banks accumulate more capital than they need for operations and regulatory requirements, paying dividends provides a mechanism to return that excess capital to shareholders. This is more efficient than holding large amounts of idle cash, which earns minimal returns. By distributing excess profits, banks can optimize their capital structure and improve their return on equity.
Meeting regulatory expectations is also a factor in dividend decisions. Banking regulators closely monitor dividend policies to ensure that banks maintain adequate capital levels. While regulators do not mandate that banks pay dividends, they expect banks to strike an appropriate balance between rewarding shareholders and maintaining capital strength. Banks that pay excessive dividends relative to their capital position may face regulatory scrutiny or restrictions on future distributions.
Competitive positioning plays a role as well. Banks that pay attractive dividends can differentiate themselves from competitors and attract investors seeking dividend income. This is particularly important in a competitive banking landscape where investors have many options for deploying their capital. A strong dividend policy can be a competitive advantage that helps a bank attract and retain institutional investors and income-focused shareholders.
How Dividends Can Affect a Bank's Stock Price
Dividends in banking can have a significant impact on stock prices, though the relationship is indirect and influenced by multiple factors. Understanding these dynamics helps investors interpret market movements and make informed decisions.
Positive market perception is one of the primary ways dividends affect stock prices. When a bank announces a dividend payment or increases its dividend, investors often interpret this as a signal of confidence by management in the bank's future earnings. This positive signal can lead to increased demand for the stock, which may push the price higher. Conversely, a dividend cut or suspension can signal financial distress and lead to selling pressure.
Dividend yield considerations also influence stock prices. The dividend yield, calculated by dividing the annual dividend per share by the stock's current market price, is a key metric for income-oriented investors. If a bank maintains or increases its dividend while its stock price remains stable, the dividend yield rises, making the stock more attractive. This increased attractiveness can lead to higher demand and a positive impact on the stock price. However, a very high dividend yield may also indicate that the market expects a dividend cut, which can have the opposite effect.
Investor behavior plays a role in how dividends affect stock prices. Some investors specifically seek out dividend-paying stocks for their income potential, while others may reinvest their dividends to purchase additional shares. Dividend reinvestment can create a compounding effect that supports long-term price appreciation. Additionally, institutional investors and fund managers often consider a bank's dividend history and consistency when assessing its attractiveness for their portfolios, which can influence the allocation of investment capital.
Market conditions and broader economic factors also interact with dividend payments to affect stock prices. During periods of economic uncertainty, investors may place a higher premium on dividend-paying stocks because they offer a predictable income stream. Conversely, during strong bull markets, investors may prefer growth stocks with higher capital appreciation potential, which can reduce the relative impact of dividends on stock prices.
It is important to note that dividends do not have a direct causal relationship with stock price movements. A bank's stock price is influenced by a wide range of factors, including earnings performance, interest rates, regulatory changes, and overall market sentiment. Investors should evaluate dividends within the broader context of the bank's fundamentals, growth prospects, and financial health rather than viewing them as the sole driver of stock price performance.
Investors should also be aware of the risks associated with dividend payments in banking. Dividends are dependent on a bank's profitability and financial health; if earnings decline, the bank may need to reduce or suspend dividend payments. Regulatory changes or increased capital requirements can also limit a bank's ability to pay dividends. Economic downturns and interest rate fluctuations can affect a bank's earnings and, consequently, its ability to maintain consistent dividend payouts. Shareholders should conduct thorough research on a bank's financial performance, regulatory compliance, and dividend policy before relying on dividends as a source of income.
In conclusion, dividends in banking serve as a vital mechanism for returning profits to shareholders while signaling financial strength and stability. By understanding the key dates, calculation methods, types of dividends, and strategic reasons behind dividend payments, investors can better evaluate bank stocks and make informed investment decisions. While dividends can positively influence stock prices and attract investors, they must be assessed within the broader context of each bank's financial health, regulatory environment, and long-term growth strategy.