When you see “TFR” on your online banking statement, it simply means “Transfer.” It is the bank’s shorthand for moving money, most commonly between your own accounts. For example, NatWest explicitly defines TFR as a “Transfer of money between NatWest accounts,” while Lloyds uses the same code to indicate an “Internal transfer between your own Lloyds accounts.”
What does online banking TFR mean?
In the context of online banking, TFR is a standardized label used by financial institutions to categorize a transaction where funds are moved from one account to another. It is not a special service or a fee, it is simply the description your bank uses to help you recognize that a transfer occurred. Understanding this code is the first step to confidently reading your statement and tracking your money, and recognizing unfamiliar transfers early helps you protect your online banking from fraud.
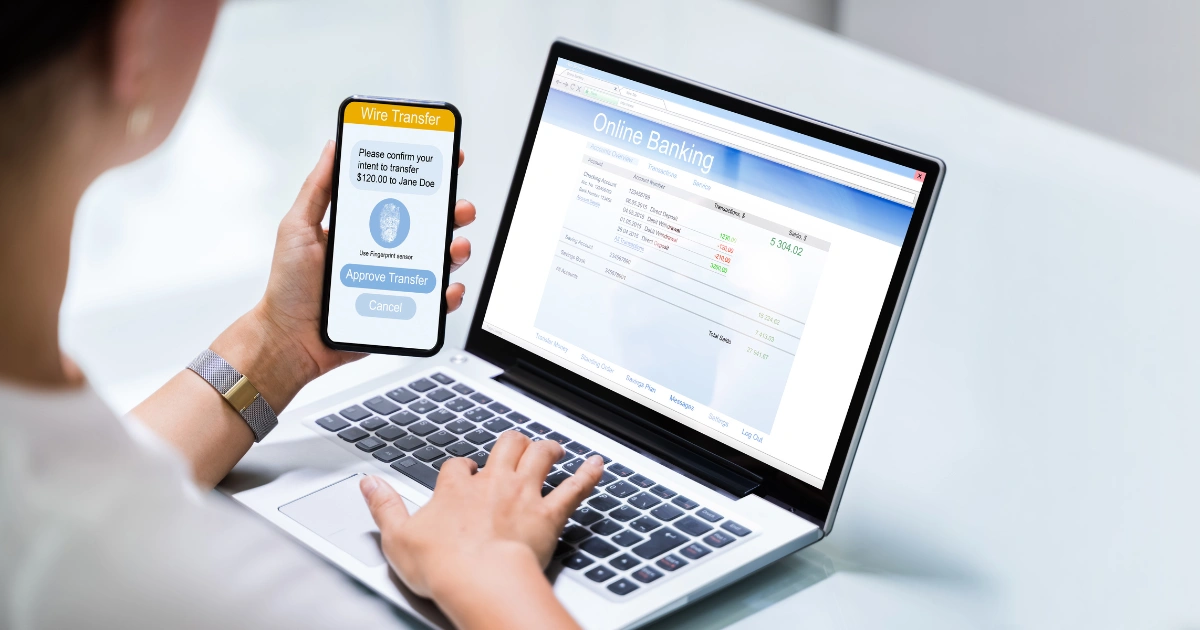
While the exact wording can vary slightly between banks, the core meaning remains consistent: TFR is a transfer of funds. This could be an internal transfer between your own checking and savings accounts, or it could be a transfer to an external account at a different bank. The key takeaway is that TFR is a neutral, descriptive term, it tells you what happened, not why or to whom.
How to spot a TFR on your statement
Most banks use “TFR” as a transaction code, but a few use a slightly different abbreviation. HSBC, for instance, uses “TRF” for the same purpose. When you review your online banking activity or a paper statement, look for this code in the transaction description column. It typically appears next to the date and amount of the transfer, and it may be accompanied by the last four digits of the destination account or a reference you entered.
To make this easier, you can use mobile banking to filter your transaction history by “transfers” or “payments.” This will isolate all TFR entries so you can quickly verify that each one is legitimate. If you ever see a TFR you do not recognize, it is worth investigating immediately, even small, unfamiliar transfers can be a sign of unauthorized access.
Common scenarios for a TFR
There are several everyday situations where a TFR code will appear on your statement. The most common is moving money from your checking account to your savings account to build an emergency fund or set aside money for a specific goal. Another frequent scenario is making a credit card payment from within the same bank, for example, transferring funds from your current account to your credit card balance. This is still an internal transfer, so your bank will label it as TFR.
You might also see TFR when you pay a loan or a mortgage held at the same institution. In all these cases, the money stays within one bank, which is why the code is so straightforward. If you transfer money to a friend or family member who banks elsewhere, the code may be different (e.g., “EXT” for external or “BAC” for bank credit), but internal transfers are almost always marked as TFR.
Managing and using transfers safely
While TFR is a routine transaction, it is still important to follow basic safety practices. Always double-check the recipient details before confirming a transfer, especially if you are sending money to an external account. A simple typo in an account number can send funds to the wrong person, and reversing that can be difficult. When you are on the go, it is wise to use mobile banking through your bank’s official app rather than a mobile browser, as the app has built-in security features that protect your login and transaction data.
Another layer of protection is to set up account alerts. Most banks let you receive a notification every time a transfer is made, so you can spot any unauthorized TFR activity immediately. Additionally, be mindful of the network you are using. Avoid making transfers over public Wi-Fi, as these connections are less secure. If you must use a public network, consider a VPN to encrypt your connection. These precautions are part of understanding the advantages and disadvantages of online banking, the convenience is immense, but it comes with the responsibility of staying vigilant.
Finally, never share your one-time passcodes or login credentials with anyone. Your bank will never ask for these via email or text. If you receive a suspicious message claiming to be from your bank, contact them directly using the number on the back of your card.
Frequently asked questions about banking transfers
How long does a TFR transfer take?
Internal transfers between your own accounts at the same bank are usually instant or complete within a few minutes. External transfers to another bank typically take one to three business days, depending on the receiving bank and the time of day you initiate the transfer. Weekends and holidays can add extra time.
What should I do if a transfer goes wrong?
If you accidentally send money to the wrong account or enter the wrong amount, contact your bank immediately. For internal transfers, your bank may be able to reverse the transaction quickly. For external transfers, they can open a dispute or trace request, but the process may take several days. Acting fast increases the chances of recovery.
How can I tell if a TFR is to someone else versus an internal transfer?
Look at the full transaction description. External transfers typically show the recipient’s name or a reference you entered. If you are unsure, you can always check your transfer history in online banking or contact customer support.
If you notice a TFR you do not recognize, check whether it matches any recent activity you initiated. If it does not, report it to your bank right away. They can help you determine if it was an error or if someone else accessed your account.