In banking, DDA stands for Demand Deposit Account, which is a checking account that gives you immediate access to your money for everyday transactions like paying bills or making purchases. Unlike a savings account or a certificate of deposit, a DDA has no maturity date and allows you to withdraw funds on demand without any prior notice. If you need to move money between institutions, an external account in banking can connect to your DDA for transfers, and you will need the banking info needed for direct deposit to set up automatic payments into it.
What a dda in banking actually means
A Demand Deposit Account (DDA) is a bank account that lets you deposit and withdraw funds on demand. Its primary function is to provide a highly liquid place for your money, meaning you can convert it into cash or use it for transactions at any time. This is fundamentally different from time deposits like certificates of deposit (CDs), which lock your funds away for a set period and charge penalties for early withdrawal. With a DDA, you have unrestricted access to your balance, making it the standard tool for managing your day-to-day finances.
How a demand deposit account works
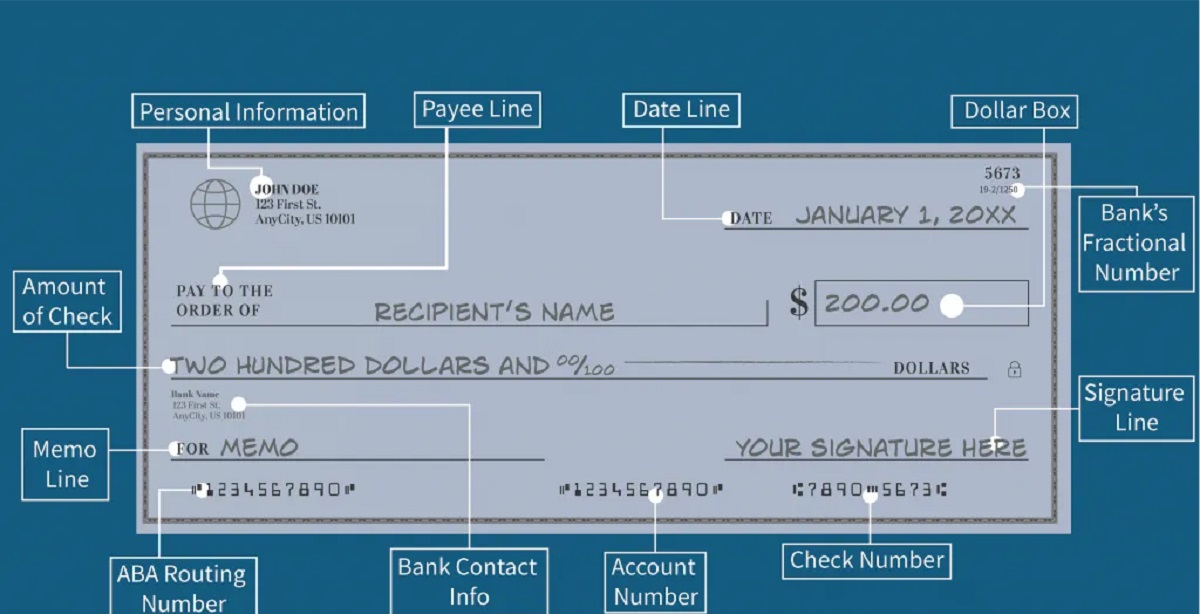
When you open a DDA and deposit money, the bank records those funds as a liability on its books. In exchange, you gain the right to access that money on demand. This is the core banking mechanics: your deposit becomes the bank's obligation to you. You can access your funds through a variety of methods, including writing checks, using a debit card at point-of-sale terminals, withdrawing cash from ATMs, and conducting electronic funds transfers (EFTs) such as online bill payments. Understanding how those card transactions work can clarify what debit mean in banking when funds leave your account. The flexibility of these access methods is a key reason why a DDA is the backbone of modern banking. If you are also tracking how banks serve local communities, the rules behind cra stand for in banking may affect where those services are offered.
Common types of DDA accounts
Financial institutions offer several categories of DDA accounts to meet different needs. Basic checking accounts provide essential features like check writing and ATM access with minimal balance requirements. Interest-bearing checking accounts let you earn a small amount of interest on your balance, though they often require a higher minimum balance. Premium checking accounts are designed for customers with larger balances and offer perks like waived fees and higher interest rates. Student accounts target young people with lower fees and educational resources. Joint accounts allow two or more people to share access to funds. Business accounts are tailored for companies, offering features like merchant services and cash management tools.
Why a DDA is required for other financial services
A valid DDA is often required to use certain financial services because it acts as a central hub for your money. For example, employers use direct deposit to send your paycheck straight into your DDA, and payment platforms like PayPal or Venmo link to it for sending and receiving money. To change a DDA on file for services like AndDone, a support request must be submitted with the reason for the change, agency name, and address, followed by providing proof of the new bank account (voided check, bank letter, or bank statement). This process ensures your new DDA is verified before it can be used for transactions.
Potential drawbacks to watch out for
While DDAs are convenient, they come with key risks tied to their usage. Overdraft fees can occur if you spend more money than you have in your account, and the bank may charge a fee for each overdraft transaction. Monthly maintenance fees are common, especially if you fail to meet certain conditions like maintaining a minimum balance. Some accounts also have minimum balance requirements, and falling below that threshold can trigger additional charges. Unlike savings accounts, most DDAs do not earn significant interest, so your money sitting in the account won't grow substantially over time.