Offline digital currency works by keeping the transaction process local and deferring final settlement until connectivity returns, a design that mirrors the physical exchange of cash but with cryptographic verification. The core principle is that your device, not a central server, holds the authority to authorize a payment, using secure hardware and local communication methods like Bluetooth or NFC to transfer value directly to another party's device. This approach is being actively explored for Central Bank Digital Currencies (CBDCs) to ensure they can function as a true digital equivalent of cash, even when the electrical grid fails.
How offline digital currency can survive a grid failure
When the electrical grid goes down, the internet and data centers that power most digital currency networks become unreachable. This is a critical vulnerability for purely online systems. To address this, developers and central banks are designing offline digital currency solutions. These systems are built on the premise that a transaction can be initiated and authenticated entirely on the user's device, without needing to contact a central server or a blockchain network in real-time. The goal is to replicate the resilience of physical cash, which can be exchanged between two people anywhere, regardless of infrastructure. This is why central banks are prioritizing "offline capabilities" in their CBDC designs, aiming to ensure that digital money remains a viable payment method during emergencies.
The hardware that makes offline transactions possible
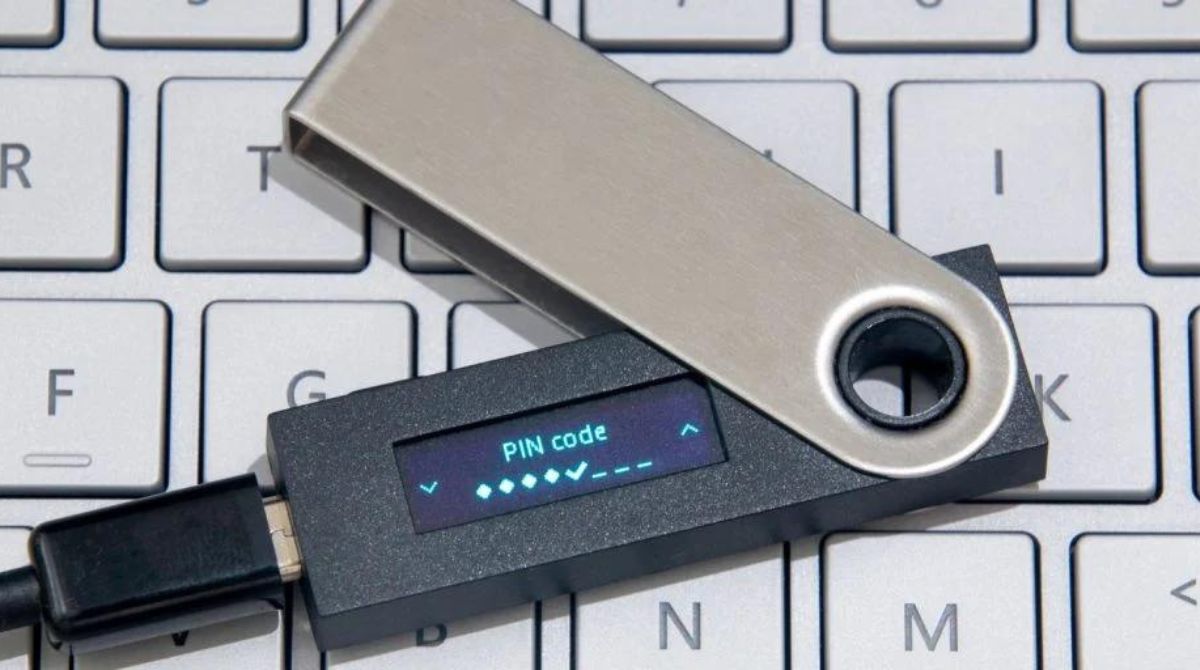
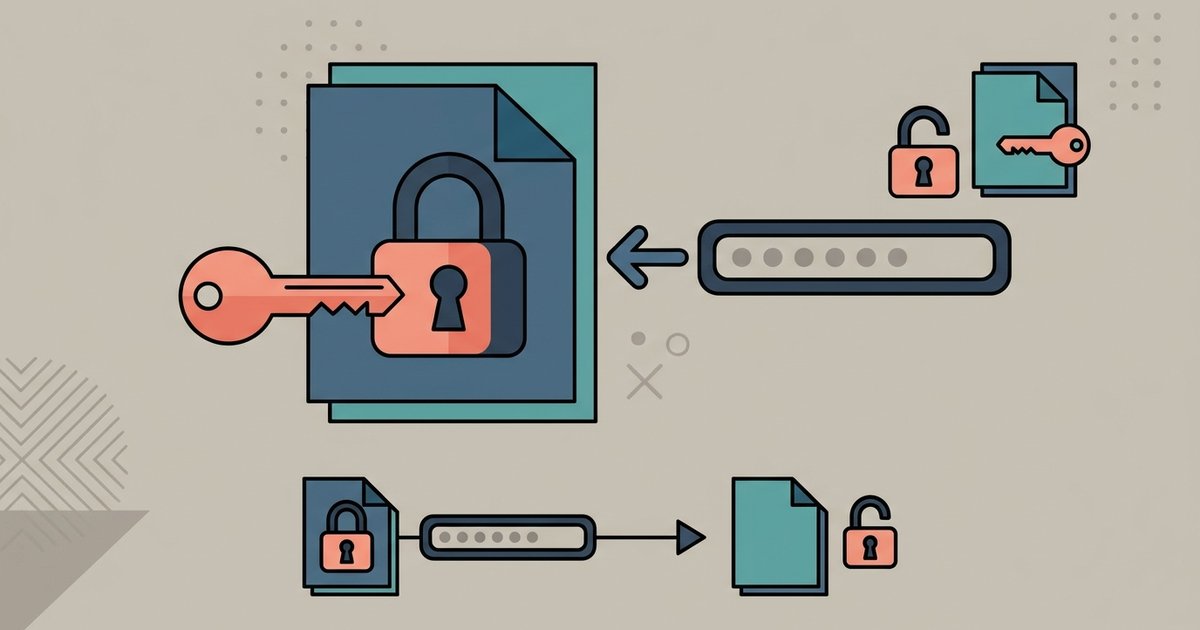
The foundation of an offline digital currency system is secure hardware. This is not just a standard smartphone; it requires a dedicated secure element that acts as a digital vault. This can be a secure enclave built into a smartphone's processor, a separate smartcard, or a dedicated hardware wallet. This secure component stores the user's private keys and digital currency balance locally, completely isolated from the internet. When a transaction is made, the secure hardware authorizes the payment by signing the transaction data with the private key, all without exposing the key to the outside world. This ensures that even if the device is compromised by malware or the network is down, the user's funds remain safe and can be spent offline.
How a peer-to-peer offline transaction actually works
An offline transaction happens through a direct, local connection between two devices. Here is the step-by-step flow:
- Connection: Two users establish a connection via Bluetooth or NFC (Near Field Communication). This creates a short-range, local network between the devices, independent of the internet.
- Transaction Initiation: The payer opens their digital wallet app and enters the amount to send. The wallet generates a transaction request that includes the recipient's public address and the amount.
- Local Signing: The payer's device sends this transaction data to the secure hardware. The secure hardware verifies the user's identity (e.g., via a PIN or biometric) and signs the transaction with the private key. This signed transaction is a cryptographic proof of authorization.
- Exchange via QR Code: The signed transaction is then converted into a QR code on the payer's screen. The recipient scans this QR code with their own device's camera. Alternatively, the recipient can generate a QR code with their address, and the payer scans it to initiate the transaction. This QR code exchange is the primary method for transferring transaction details offline.
The critical step: reconciling with the ledger later
It is a verified fact that an offline transaction is not final until the device reconnects to the network. The transaction is recorded locally on both devices as a pending debit and credit, but it has not been added to the central ledger. When the device regains internet or cellular connectivity, it broadcasts all stored offline transactions to the network. This is when the central ledger (e.g., a CBDC database or a blockchain) processes the transaction, verifies its authenticity, and permanently records it. This delay is necessary because it is the only way to ensure that the same digital currency unit has not been spent twice in the real world. The system relies on the eventual synchronization of all local records with the authoritative central ledger.
The double-spending problem and how it's managed
The most significant risk with offline digital currency is the increased potential for double-spending. In a real-time online system, the central authority can immediately check if a digital coin has already been spent. Offline, this is impossible. A malicious user could theoretically sign two different transactions with the same funds, one for a merchant and one for another party, while offline. To mitigate this, offline systems implement strict security models and limits. These include:
- Spending Limits: Users are often limited in the amount they can spend in a single offline transaction or within a specific time frame. This limits the potential loss from a single fraudulent act.
- Reconciliation and Fraud Detection: When the device reconnects, the central system checks for double-spending. If a conflict is detected, the system can identify the fraudulent party and reject the transaction. This is why offline transactions are not considered final until they are reconciled.
- Reputation and Trust: In a peer-to-peer network, users are encouraged to transact only with trusted counterparts. The system can also track the transaction history of users to identify suspicious patterns that might indicate an attempt to double-spend.
Why offline capability is crucial for the future of digital cash
The ability to function offline is not just a convenience; it is a fundamental requirement for digital currency to replace physical cash. For CBDCs to be a true alternative to banknotes, they must work in every scenario where cash is used today, including during natural disasters, internet blackouts, or in remote areas with poor connectivity. Offline functionality ensures financial inclusion for the unbanked and underbanked populations who may not have reliable access to the internet or a smartphone with a data plan. It provides a resilient fallback that guarantees access to money and the ability to make payments, even when the digital infrastructure is compromised. Without this capability, a digital currency would be a fragile tool, leaving millions vulnerable during emergencies and failing to serve as a universally accessible form of public money.