In most cases, no—once your phone number, email, or identity is flagged and banned by Zelle’s network for fraud or severe policy violations, the decision is final and you cannot simply reopen the account. You may have a narrow path to appeal only if the ban was a bank-specific risk decision rather than a network-level fraud blacklist, and even then success is rare.
The difference between a bank lock and a reopen Zelle account ban
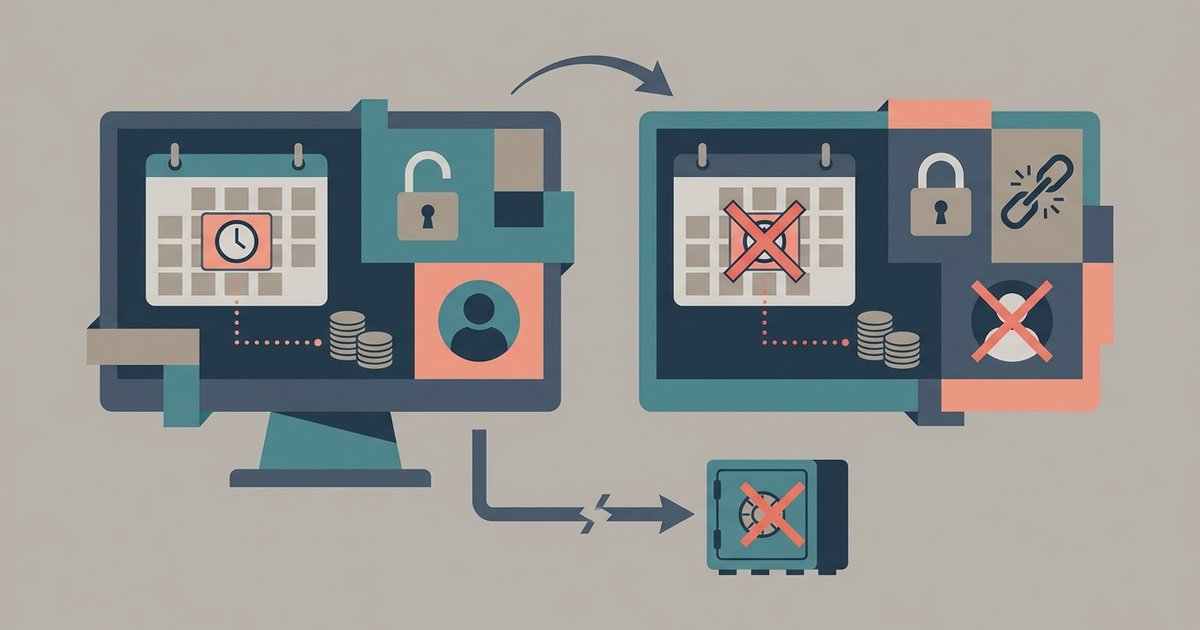
A bank lock is a temporary security freeze your financial institution places on your Zelle access. It is often triggered by unusual login attempts, a forgotten password, or a suspicious transaction. This is reversible. Call your bank’s fraud department or visit a branch to verify your identity. Within a few business days you will be able to unlock your Zelle account. A network ban, however, comes from Early Warning Services. This company operates Zelle’s network and risk management. It blacklists your identity, phone number, and email across all participating banks. This ban is permanent because it is tied to confirmed fraud, chargebacks, or repeated terms-of-service violations. Your bank cannot override a network-level ban. The block follows you even if you switch institutions. If you see an error indicating a permanent restriction, you are facing a network ban. A message indicating you are no longer eligible for Zelle means the same thing. This is not a simple bank lock.
How to submit an appeal that might actually be read
Generic customer service agents at your bank cannot overturn a Zelle network ban. They lack access to Early Warning’s enforcement records. To submit a meaningful appeal, you must reach your bank’s executive escalations team or risk department. Call your bank’s main line and request to be connected with a department that can handle a manual review of your Zelle ban. Explain that you need a manual review of your Zelle ban. Inquire whether they can submit a dispute to Early Warning Services on your behalf. Provide any documentation that supports your case. For example, include a police report if you were a fraud victim. Show proof that a disputed transaction was legitimate. Prepare for an extended waiting period. Understand that the decision is final. Your appeal will almost certainly be denied if the ban was based on a chargeback. The same is true if you sent payments to flagged accounts. No amount of polite requests to “get a Zelle account” through standard support channels will bypass this process.
What people get wrong about opening a new account
Many banned users believe they can sign up with a new email or a different phone number. Some try a bank that does not currently use Zelle. This is a critical mistake. Early Warning Services cross-references your Social Security number, driver’s license, and device identifiers across its entire network. Attempting to bypass a ban by creating a new profile triggers an automatic flag. This can lead to permanent blacklisting. It can also restrict other financial products like checking accounts or credit cards. You cannot work around the system by linking Zelle with multiple accounts at the same bank or across different banks. The network sees your identity, not your account number. You will likely encounter an immediate error if you try to open a new Zelle profile. Look for messages indicating enrollment failure or that the phone number is already in use. A future review could retroactively ban you again even if you succeed at first. The only legitimate path is the appeal process described above. No third-party service or trick can reset the network’s records. A Zelle limit reset applies only to daily or weekly sending caps on an active account. It has no effect on a permanent ban. Accept the decision if you are banned. Use alternative payment methods like wire transfers or paper checks going forward.
Unlike a simple bank lock, a permanent Zelle network ban blacklists your identity across all participating banks and cannot be overridden by your financial institution.